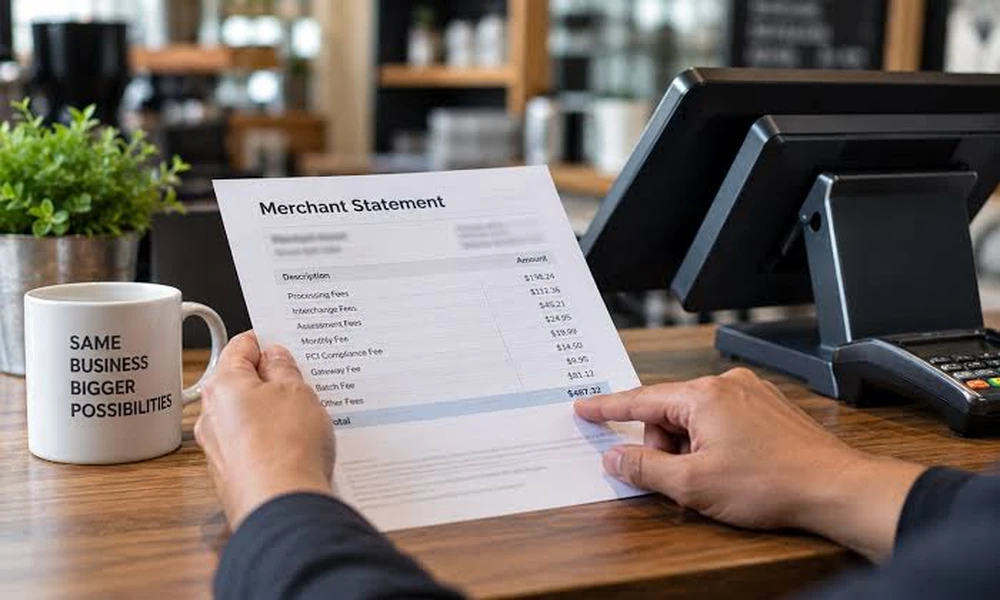
Visa and Mastercard swipe fees in the United States reached $118.8 billion in 2025, up from $111.2 billion the year before, according to the Merchants Payments Coalition. For one shop, salon or service company, that national figure becomes a few pages of PDF that arrive each month and rarely get read past the total. The statement is still the only document that shows where each dollar of card cost goes. Learning to read it is the most reliable way to judge whether a rate quote holds up.
Merchants in Dallas, Fort Worth, Plano, Frisco and Irving who want a second set of eyes on those pages can request a free processing fee evaluation from American Bank Cards, the DFW Card Services team that has worked with Texas businesses since 1995. Accounts run on interchange plus pricing with no long-term contracts. They include free PAX payment terminals and cover in-person, online and mobile payments with PCI-compliant encryption, deposits in as little as 24 hours, and support around the clock. Bring a recent statement to the review, and the line items below become much easier to compare.
Start With the Summary Page
The first page usually shows total sales volume, total fees and the deposit totals. Divide total fees by total volume and you get your effective rate. A business that processed $40,000 and paid $1,140 in fees has an effective rate of 2.85%.
That number is a sanity check, not a verdict. It moves with your card mix. A month heavy with rewards cards or keyed transactions will look worse than a month of tapped debit cards, even if nothing in your pricing changed. Compare it month over month, and always read it alongside the interchange total on the following pages.
Also scan the message box. Processors often announce fee changes there in small type, and that is where a new monthly charge first appears.
The Interchange Section
This is usually the longest part of the statement, and it can run several pages. A few terms explain most of it.
Interchange. The fee paid to the bank that issued your customer’s card. The card networks set these rates, and they vary by card type, entry method and your business category. Every processor passes the same interchange through, so nobody can legitimately discount it.
Downgrades. When a transaction is missing data or settles late, it can clear at a costlier category than it otherwise would. Keyed entries, batches closed a day late and missing address verification are common triggers.
Regulated debit. Under the Federal Reserve’s Regulation II debit interchange rules, large issuers with $10 billion or more in assets are capped at 21 cents plus 0.05% of the sale, with a one cent fraud prevention adjustment. Cards from smaller banks and credit unions are exempt and often cost more. A lower cap has been proposed, and the rule is being fought in the appeals courts, so this figure could change.
Network Fees Sit Beside Interchange
Assessments. Visa, Mastercard and Discover each charge a small percentage of volume, generally in the range of a little over a tenth of a percent.
Per-item network fees. These are small charges per transaction or authorization, along with extra fees when a customer pays with a card issued outside the country.
Both are pass-through costs. If your statement lumps them together with the processor’s own charges under one vague label, ask for a breakdown.
| Statement line | Who keeps the money | Same at every processor? | What to check |
|---|---|---|---|
| Interchange | Card-issuing bank | Yes | Downgrades and keyed transaction volume |
| Card brand assessments | Visa, Mastercard, Discover | Yes | Billed at cost, not marked up |
| Processor markup | Your processor | No | Percent and per-item fee match your agreement |
| Monthly account fees | Your processor | No | Statement, gateway, batch and minimum fees |
| PCI non-compliance fee | Your processor | Avoidable | Whether your annual SAQ is on file |
| Chargeback fees | Your processor | No | Number of cases and the per-case charge |
Where the Processor’s Margin Shows Up
How the margin appears depends on the pricing model. On interchange plus, the markup is shown as a fixed percentage plus a per-transaction fee on top of the true cost. That makes it easy to audit, because you can recalculate it yourself.
Tiered pricing sorts sales into qualified, mid-qualified and non-qualified buckets. The spread between what interchange actually cost and what you were billed stays hidden inside those buckets. Flat rate pricing is simple to read, but it bundles everything together, so you cannot see what you are paying the processor versus the card networks.
Then look past the transaction fees. Monthly minimums, annual fees billed in a single month, and early termination clauses in the merchant agreement often cost more over a year than a tenth of a point on the rate.
The PCI Line Item
Every merchant that accepts cards falls under PCI DSS. The current version is 4.0.1, and the 51 requirements that were once optional best practices became mandatory on March 31, 2025. Some of them target online checkout pages, including controls over the scripts that run on a payment page. The PCI Security Standards Council has published guidance on those e-commerce requirements, including recent changes to the SAQ A questionnaire.
Most small merchants validate once a year with a self-assessment questionnaire. If that questionnaire lapses, many processors add a monthly non-compliance fee until it is filed. Encrypted terminals and hosted payment pages shrink how much of your setup falls in scope. That makes the questionnaire shorter and easier to keep current.
Reading the Statement Against New Rules
The revised Visa and Mastercard settlement announced in November 2025 received preliminary court approval in June, and final approval is still pending. As proposed, it would:
- lower interchange by 0.1 percentage point for five years
- cap standard consumer card rates at 1.25% for eight years
- let merchants decline categories such as premium or commercial cards
It would also widen surcharging rights. Merchants could surcharge credit cards at the brand or product level, limited to the lesser of 3% or their actual cost of acceptance. None of these changes apply until approval is final and the networks notify merchants.
That cost of acceptance figure comes straight from your statement, which is one more reason to understand it. Debit and prepaid cards cannot be surcharged under any of these rules. Surcharges also require clear disclosure at entry and checkout, the dollar amount printed on the receipt, and advance notice to your processor.
Texas adds its own layer. The state’s credit card surcharge statute has been challenged in federal court over the years, so get current legal advice before adding a credit surcharge. The Texas Attorney General has also noted, in an opinion on surcharges and cash pricing, that the law does not stop a seller from offering cash customers a lower price. That distinction is why many Texas merchants choose cash discount programs, where the posted price is the card price and paying cash earns a reduction.
Reading a statement this way turns a monthly bill into a record you can question line by line. Interchange and network fees are fixed for everyone. Everything else is negotiable, avoidable or worth asking about, and the pages that arrive each month already hold the evidence.
